
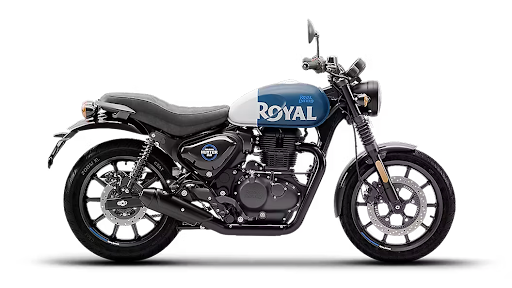
Buying a Hunter 350 through a bike loan need not involve a complicated paperwork exercise, but there is no universal two-document approval rule. The records required depend on the lender, your employment type and how it verifies identity, income and repayment capacity. Preparing a small, accurate document set in advance can make the application easier without assuming that approval is automatic.
What lenders commonly need to establish
A financing provider usually checks who you are, where you live and whether your finances can support the proposed monthly instalment. PAN, an accepted identity or address document and a recent photograph may form part of the verification process. Digital identity checks can reduce paper handling where available, but they do not remove the underlying verification requirement.
Income evidence is another distinct step. Some lenders rely on banking records or internal eligibility assessments; others request salary slips, tax records or proof of business earnings. Requirements vary by case, and a dealer cannot guarantee that every applicant will qualify with the same few documents.
A practical checklist for salaried riders
If you receive a regular salary, keep your PAN details and current address record ready. Ensure the name and date of birth shown across documents match. Have recent salary evidence and the bank statements requested by your chosen lender available, even if an online application initially asks for fewer uploads.
Check whether your employer’s name, current work address and monthly take-home pay are entered accurately. A change of job, probation period or irregular bonus may affect how a lender assesses income. Do not state gross salary as disposable income: rent, family commitments and existing instalments still matter when deciding what you can safely repay.
What changes for self-employed applicants?
A freelancer, shop owner or independent professional may need bank transactions and income-tax or business records to demonstrate earnings. A lender might also request business registration or other activity evidence where applicable. There is no single checklist that fits all occupations, so ask for the precise list before travelling to the showroom.
If your income varies seasonally, calculate repayment capacity using a quieter month rather than your strongest sales period. A larger initial contribution can reduce the financed balance, but it does not replace the lender’s affordability and identity checks. Keep personal and business transactions understandable if the finance provider asks about them.
Does the Hunter 350’s price determine approval?
The Hunter 350 uses a 349 cc Royal Enfield single-cylinder engine, but its mechanical specification is not an eligibility test. Financing depends on the approved amount, the chosen variant, your credit profile and the lender’s policies. The motorcycle’s price affects how much you may need to borrow, while its model name alone does not establish a guaranteed loan entitlement.
Before applying, obtain an itemised ex-showroom quotation and identify insurance, registration and accessories separately. Ask which cost components the lender can finance. A quotation that rolls optional items into one total can make it difficult to understand the real principal and down payment.
Assess an instalment before uploading documents
For illustration, a loan of Rs. 1,50,000 over 36 months with an assumed 12% yearly reducing rate produces an EMI of roughly Rs. 4,982. This is a mathematical example, not a live Hunter 350 offer. The actual repayment may differ because of the approved rate, amount, tenure and associated charges.
Test a more demanding budget month. If fuel, insurance provision, parking and existing debts would leave little spare money after the EMI, consider a larger down payment or a less expensive choice. A longer tenure may lower the monthly amount but commonly increases total interest. Lenders assess eligibility; you should independently assess comfort.
Ways to avoid unnecessary application delays
Enter your legal name consistently, use a mobile number you can access for verification and upload clear, complete images where requested. If an address has recently changed, ask what additional proof is acceptable rather than altering information to fit an old record. Provide accurate existing-loan details and avoid multiple inconsistent applications in a short period.
Review the credit report for errors where possible. A low or limited credit history does not automatically produce the same decision with every lender, but mismatched data can slow verification. Never share an OTP or banking password with a salesperson; complete authentication through the authorised application channel.
Understand the agreement before paying anything
Request a written summary of interest, processing fees, repayment dates, penalties and early-settlement rules. Check whether an upfront booking amount is refundable if finance is declined. Confirm who receives the disbursal and when delivery and registration will occur. Store the sanction letter and signed agreement with your invoice.
If the lender asks for additional documents after preliminary approval, supply them through a verified route. A provisional approval is not the same as a final sanction. This distinction protects you from promising a delivery date before the financing is settled.
A simpler Hunter 350 application starts with preparation
Gather accurate identity, address and financial information, ask your selected lender for its actual checklist and calculate an affordable instalment before committing. The aim is not to minimise documents at any cost; it is to avoid repeated requests and misunderstandings. A clear application and a repayment plan that fits your income make ownership more manageable.




Leave a Reply